The market
The five myths about buying commercial in the Hunter.
Each one tested against the settled record — deal-level, corrected.
Myth 1 of 5
The assumption — “You need $5 million to buy commercial.”
Half the Hunter’s commercial deals over $1.5M settle below $3.0M — and the entry tier starts where a Newcastle investment house ends.
Source: NSW Valuer General settled transactions, deal-level, corrected.
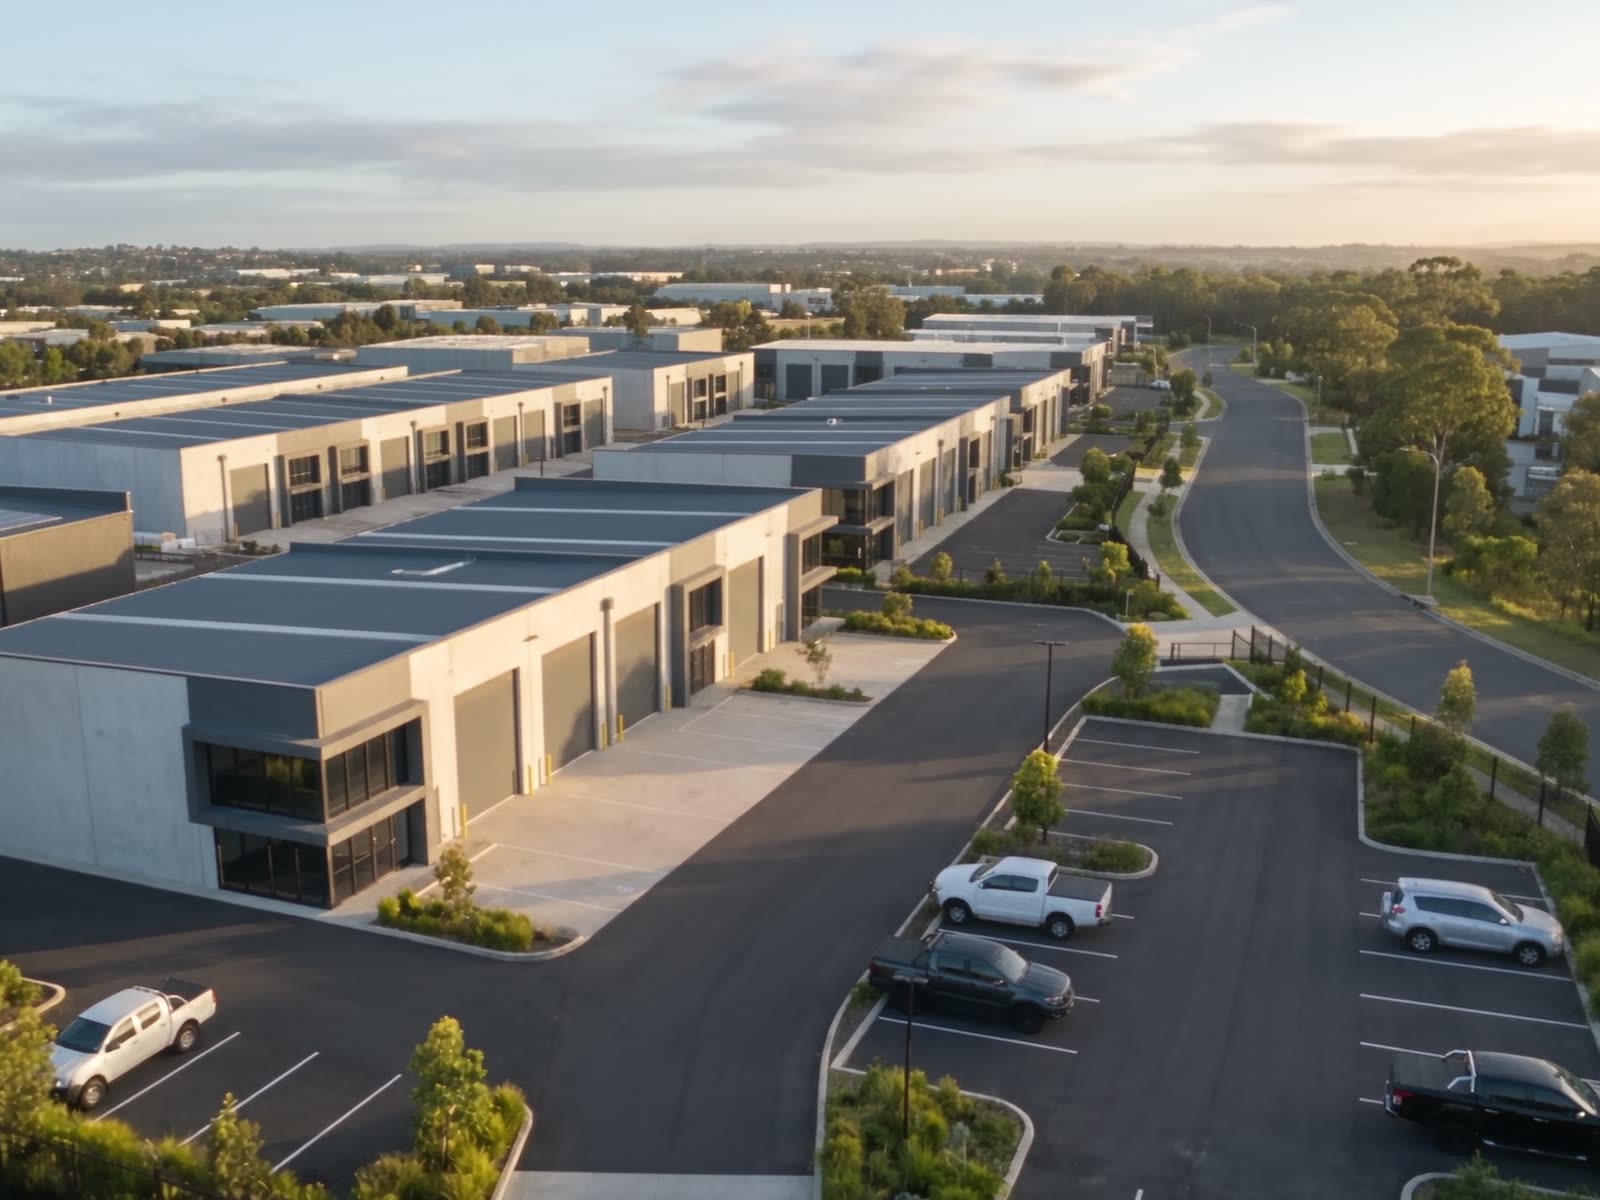
Myth 2 of 5
The assumption — “Commercial is riskier than residential.”
The risk is different, not bigger: commercial tenants pay the outgoings and sign for years, not months.
Not our data Term ranges per published agency leasing research (Knight Frank, Colliers) and standard NSW residential tenancy practice — not drawn from the settlement data above.
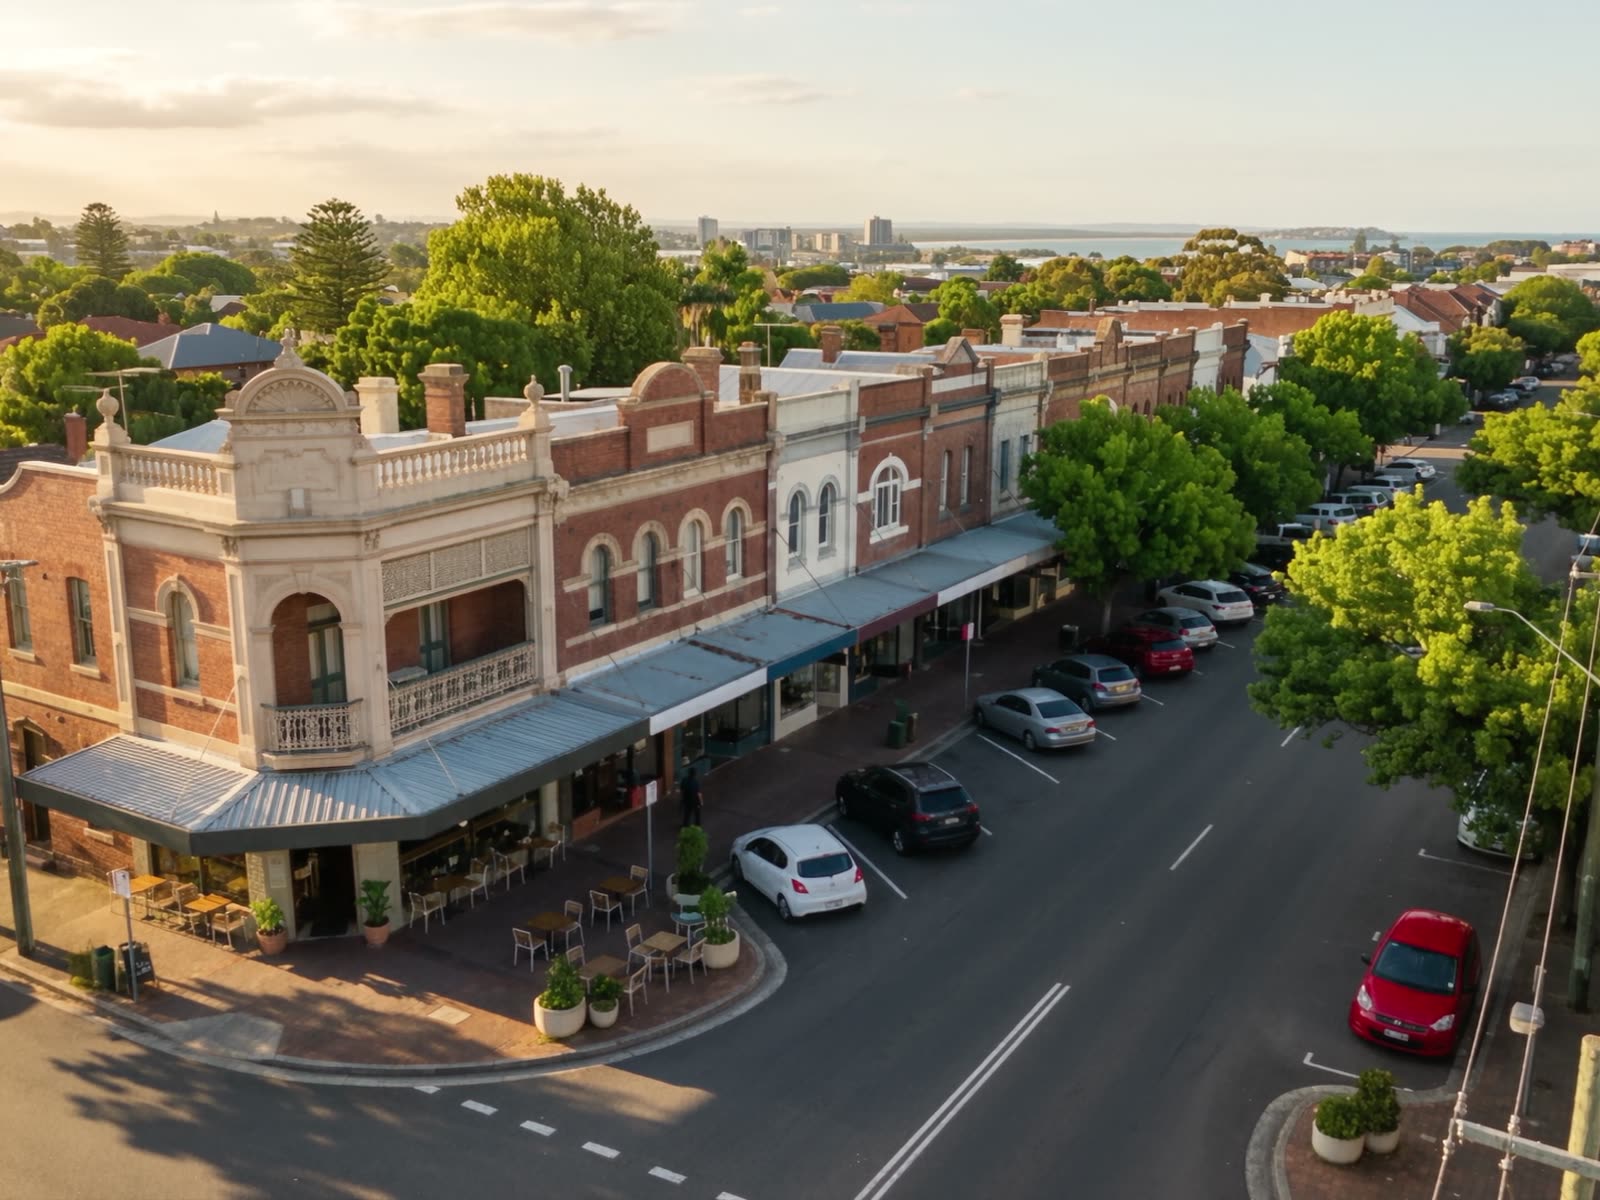
Myth 3 of 5
The assumption — “Banks won’t lend on commercial.”
Commercial lending is routine — the difference is the rent typically services the debt from day one.
Not our data Source: RBA Bulletin, Financial Stability Risks from Commercial Real Estate (September 2023) — most Australian bank commercial property loans are written below 65% LVR; bank maximums typically run 65–75%. Not drawn from the settlement data above.
Myth 4 of 5
The assumption — “The yields aren’t worth the hassle.”
Net commercial yields in this market run roughly double gross residential — and net means after the tenant pays the outgoings.
Gross yield is rent over price, before any costs. Net is what is left after outgoings — and in commercial, the tenant typically pays those.
Not our data Sources: Knight Frank Newcastle industrial market research (2025) — market yields around 5.75–6.25% — and CoreLogic-reported gross residential house yields (about 3% nationally, lower in Newcastle). Not drawn from the settlement data above.
Myth 5 of 5
The assumption — “You need to be a property expert first.”
No — you need to know what the asset is worth, what the lease is really saying, and when to walk. That’s the job you’re hiring.
Most of what we assess, we reject.